#4
NCBA
NCBA Loop: Reinventing Digital Banking for a Mobile-First Generation
Kenya has long been recognized as one of Africa’s most innovative digital finance markets. From mobile money to digital lending, the country has repeatedly demonstrated how technology can redefine the way people access financial services. In this rapidly evolving ecosystem, banks are increasingly embracing digital-first platforms designed for a younger, mobile-savvy generation.
One such innovation is LOOP, the fully digital banking platform developed by NCBA. Designed as a lifestyle-driven financial ecosystem rather than a traditional bank account, LOOP reflects the shifting expectations of modern consumers—particularly millennials and Gen Z—who demand convenience, speed, and personalization in their financial lives. To the digital generation, “Digital banking is no longer just about transactions—it is about enabling lifestyles.”
“LOOP was designed to move beyond traditional banking, offering a fully digital lifestyle platform built around the way people actually live and spend.”
Launched as a mobile-first solution, the platform combines payments, savings, credit, and lifestyle rewards within a single app. In doing so, it signals a broader transformation taking place across Kenya’s banking sector as financial institutions compete not only with each other but also with fintech startups and mobile money providers.
Traditional banking models have often struggled to appeal to younger consumers accustomed to seamless digital experiences in areas such as shopping, entertainment, and social media. Recognizing this shift, NCBA developed LOOP as a platform that reimagines how a bank interacts with its customers.
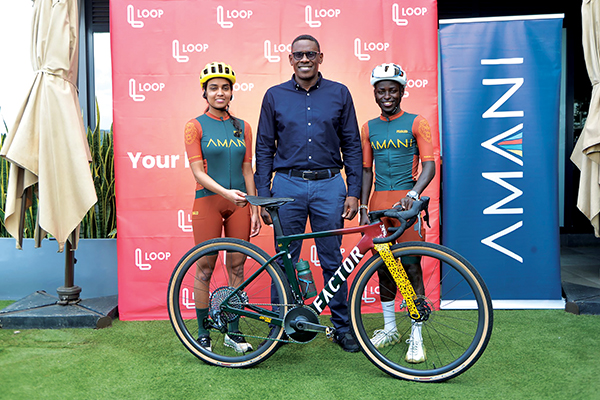
Rather than focusing solely on accounts and transactions, the platform integrates financial tools with lifestyle features that support everyday activities—from budgeting and saving to entertainment spending and online shopping. To borrow the viral adage, “The modern customer does not want to visit a bank branch—they want their bank to live inside their smartphone.”
Through the LOOP mobile app, users can open an account in minutes, receive a digital debit card, transfer funds, track spending, and access credit facilities without stepping into a banking hall.
This approach reflects a broader industry trend toward branchless banking, where digital platforms replace physical infrastructure as the primary point of customer engagement.
What distinguishes LOOP from conventional mobile banking platforms is its focus on lifestyle integration. The platform combines core financial services with everyday conveniences, creating a digital ecosystem that extends beyond basic banking-a lifestyle ecosystem.
Key features include:
- Instant account opening through the mobile app
- Digital and physical debit cards for payments and ATM withdrawals
- Expense tracking and budgeting tools
- Savings goals and automated savings options
- Digital loans and overdraft facilities
- Lifestyle rewards and partner discounts
By integrating these services into a single digital platform, NCBA aims to position LOOP not simply as a banking product, but as a financial companion for everyday life.
Kenya’s financial landscape is among the most competitive in Africa. Mobile money platforms transform how individuals send and receive money, while a growing number of fintech startups are offering digital savings, lending, and investment tools.
In response, banks have increasingly invested in digital innovation to remain relevant in a mobile-first economy.
For NCBA, LOOP represents a strategic move to capture a younger customer base that might otherwise bypass traditional banking services entirely. In order to survive and grow in the current environment in the era of fintech disruption, banks must evolve into technology platforms.
By offering a fully digital onboarding process, intuitive user experience, and lifestyle features that resonate with younger consumers, LOOP positions NCBA as a bank that understands the expectations of a new generation.
Another key advantage of digital platforms like LOOP lies in their ability to harness data. By analyzing customer behaviour—such as spending patterns, savings habits, and financial goals—the platform can offer personalized financial insights and tailored credit products. After all, it is the era of data-driven banking.
This data-driven approach enables the bank to provide more responsive and flexible services while improving risk management, while at the same time offer smarter, more personalized services.
For example, spending analytics within the app help users understand where their money goes each month, encouraging better financial planning and budgeting.
Such features align with the broader global shift toward financial wellness, where banks help customers manage their money more effectively rather than simply providing transactional services.
Beyond convenience and innovation, digital banking platforms also play an important role in expanding financial inclusion. By removing the need for physical branches and lengthy paperwork, LOOP lowers the barriers to entry for many potential customers.
This is particularly significant in emerging markets where traditional banking infrastructure may not reach all communities.
Through mobile onboarding and digital identification systems, LOOP allows users to open accounts quickly and securely, bringing more individuals into the formal financial system. In essence, “Digital platforms like loop have the potential to bring millions of previously underserved consumers into the banking ecosystem. These platforms represent the future of banking. For NCBA, LOOP represents an important step in that transformational vision.
The platform demonstrates how traditional banks can leverage technology to remain competitive in an era dominated by mobile-first consumers and fintech innovation. Going by the success of products like LOOP, “The future of banking will be defined not by buildings, but by platforms.”
As Kenya continues to lead Africa in digital financial innovation, initiatives such as LOOP highlight how banks are adapting to meet the expectations of a new generation—one that expects financial services to be instant, intuitive, and seamlessly integrated into daily life.
In a country where the smartphone has already revolutionized money, the next chapter of banking may well be written in apps like LOOP.