#8
ABSA BANK
Absa Bank Kenya: Meeting the Realities of a Changing Banking Market
Kenya’s banking sector has spent the past decade adjusting to a difficult set of realities: a mobile-first consumer base, intense competition from fintech lenders, tighter regulation, and an economy where millions still operate outside formal finance. Every major bank now claims to be “digital” and “customer-centric.” The real question is whether those claims translate into measurable shifts in how credit, savings, and financial services reach Kenyan households and businesses.
Absa Bank Kenya has spent the past several years attempting to answer that question through a mix of digital lending, targeted financial products, and new distribution channels. The strategy reflects both pressure and opportunity. Kenya is one of Africa’s most sophisticated financial markets, where competition from mobile platforms and challenger lenders has eroded the advantages traditional banks once held.
Absa’s response has been to rebuild its consumer banking model around speed, access, and product specialization. The results reveal both the promise and limits of modern banking in Kenya.
One of the fiercest battle fronts is Digital Credit. Digital lending has become one of the most contested spaces in Kenya’s financial sector. Mobile operators, fintech startups, and commercial banks all compete for a consumer base that increasingly expects credit to be instant and mobile.
Absa entered that market with Timiza, a digital lending platform designed to extend unsecured credit through mobile channels. The platform allows customers to apply for loans, manage accounts, and access other services without visiting a branch.
According to the bank’s disclosures, the platform disbursed approximately KSh25.1 billion in loans in 2024. That figure illustrates how quickly digital credit has become a core part of retail banking in Kenya.
The model is straightforward. Algorithms assess risk using transaction history and other behavioural data. Loans are issued quickly, often in small amounts, and repayment cycles are short.
For borrowers, the appeal is obvious: speed and accessibility. For banks, the model provides a new way to reach customers who may never walk into a traditional branch.
But digital lending in Kenya also carries risks. Regulators have tightened oversight after years of complaints about predatory rates, aggressive collections, and consumer over-indebtedness in the mobile credit sector. Any bank expanding in this space must balance growth with responsible lending.
Absa’s bet is that established institutions, with stronger compliance structures and deeper capital buffers, can operate digital credit more sustainably than many fintech startups. Whether that assumption holds will depend on how carefully the bank manages credit risk as volumes grow.
The second focus area for Absa is looking beyond transactions. Traditional banking once revolved around deposits, loans, and payments. That model is shifting. Financial institutions increasingly position themselves as long-term financial partners rather than transaction processors.
Absa has reorganized parts of its retail strategy around that idea. Instead of focusing purely on products, the bank groups services around life stages and financial needs—entrepreneurship, home ownership, wealth building.
It is a subtle but important shift. Kenyan consumers are more financially literate and are quickly becoming more sceptical of banks than they were a decade ago. Many now maintain accounts with upwards of three banks while a sizeable number at the bottom third of the pyramid are making do with mobile money platforms. Customer retention has since become dependent less on brand loyalty and more on value creation. As a result, advisory services, financial planning, and bundled financial solutions have become part of Absa’s effort to deepen those relationships.
Sustainability has become a defining theme in global finance. In Kenya, where energy costs remain high and climate shocks increasingly affect agriculture and infrastructure, the issue of financing the climate transition, now carry more economic weight than before. Towards this end, Absa has introduced an Eco-Home Loan, designed to finance housing that incorporates energy-efficient or climate-resilient features. The loan allows homeowners to install solar panels, water-efficient systems, or other technologies that reduce energy consumption.
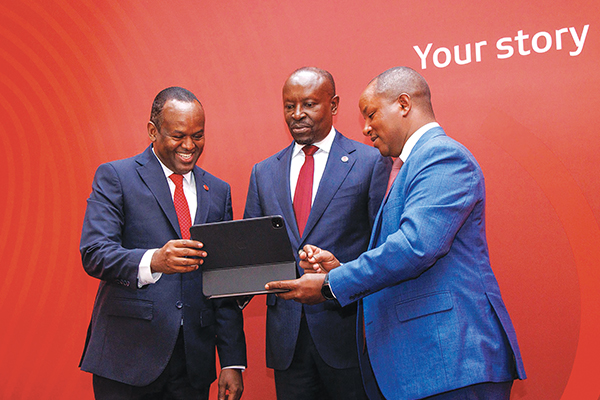
For the bank, the initiative serves several purposes. It supports Kenya’s national climate commitments, expands the mortgage market, and positions Absa Bank within the growing field of green finance.
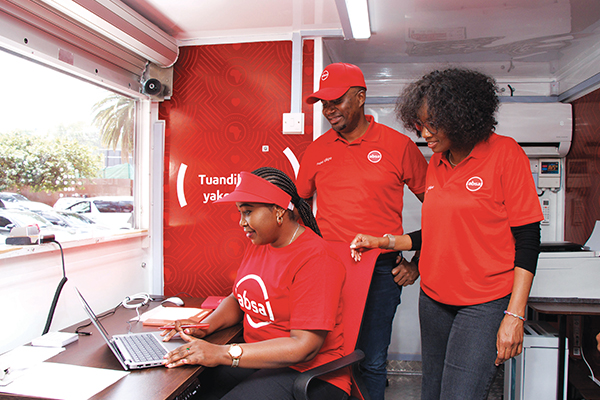
Absa has introduced mobile service units known as “Branch on the Move.” The solar-powered, cashless units travel to underserved areas and provide services such as digital account onboarding and instant debit card issuance.
Absa has also launched Service Pods—small, lounge-style banking spaces located in shopping malls and other high-traffic areas. These operate outside traditional branch hours and emphasize advisory services rather than transactions.
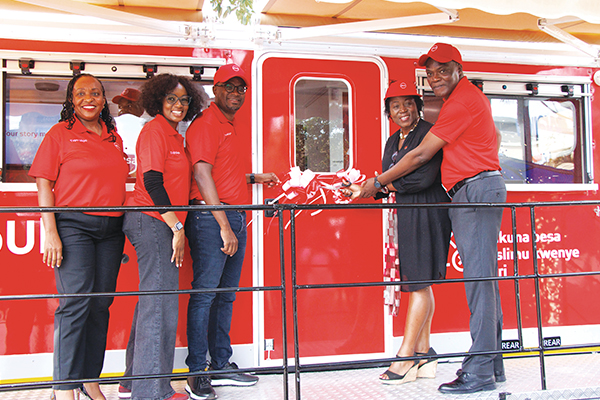
Both initiatives reflect an acknowledgment that Kenya’s financial system will remain hybrid for sometimes to come. While mobile platforms dominate daily transactions, physical presence matters most for trust and accessibility.
Observers view Absa Bank Kenya as the most complete bank in 2025 with the best mix of growth, profitability and a strong balance sheet supporting profit growth, with the bank winning in execution. As a balanced universal bank, Absa Bank Kenya is strong in retail, corporate and SME, displaying a consistent earnings growth in 2025. For instance, the shareholder returns rose by over 17% in 2025, representing a dividend payout of KES 2.05 per share.